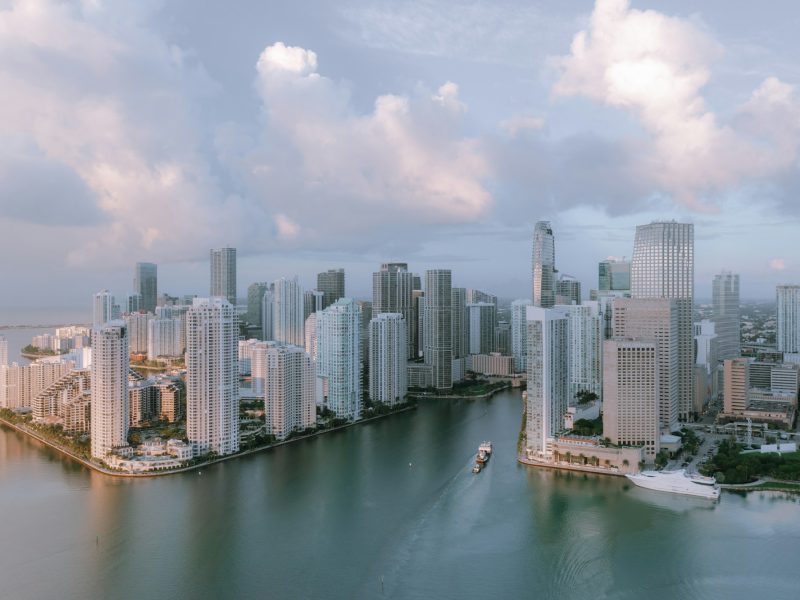
Buying your first home is exciting and a little intimidating, especially in a market as fast-moving and varied as Miami. The good news: the process is the same for everyone, and if you take it one step at a time you will avoid most of the surprises.
Step 1: know your numbers
Before you look at a single listing, work out what you can comfortably afford. Lenders will tell you how much you can borrow; only you can decide how much you want to spend every month.
In Miami, your monthly cost includes more than the mortgage:
- Principal and interest on your loan.
- Property taxes, typically 1.7% to 2.1% of the purchase price per year.
- Homeowners insurance, which can be significant for older homes and properties near the water.
- Flood insurance, if the home is in a flood zone.
- HOA or condominium fees for most condos and many townhouses.
Use the mortgage calculator on any Doorstep listing to see a full breakdown.
Step 2: get pre-approved
A pre-approval letter shows sellers you are serious and tells you exactly how much you can borrow. Shop at least two or three lenders, compare their rates and fees and ask about first-time buyer programs. Florida offers down payment assistance through Florida Housing, and Miami-Dade County runs its own programs for eligible buyers.
Step 3: choose your neighborhoods
Miami’s neighborhoods are very different from each other. Think about your commute, schools, walkability and lifestyle, then pick two or three areas to focus on. Our neighborhood guides are a good place to start.
Most first-time buyers start with a wish list and end up with a priority list. Decide what you truly can’t live without before you start touring.
Step 4: tour and make an offer
Your agent will set up showings, help you compare homes and pull recent sales data so your offer is grounded in the market. In Florida, most residential purchases use a standard contract with an inspection period, a financing contingency and an appraisal contingency.
Condos need extra homework
If you are buying a condo, ask for the association’s budget, reserve study, milestone inspection report (for buildings three stories or taller) and meeting minutes. These documents reveal whether special assessments are coming.
Step 5: inspections and appraisal
During the inspection period, hire a licensed home inspector and, for older homes, a wind-mitigation and four-point inspection, which insurers often require. If the inspection reveals problems, you can ask the seller to repair them, offer a credit or walk away within the inspection period.
Step 6: closing
Your lender will finalize the loan, the title company will check that the property has a clean title and you will sign your documents — often at the title company’s office or remotely. Bring a cashier’s check or wire the funds for your down payment and closing costs, which in Florida typically run 2% to 5% of the purchase price.
Common mistakes to avoid
- Changing jobs or opening new credit cards before closing.
- Skipping the inspection to make your offer more competitive.
- Underestimating insurance costs.
- Ignoring the condominium documents.
- Forgetting to budget for moving, furniture and repairs.
Budgeting for the first year
Once you have the keys, plan for the costs that arrive in the first twelve months. Set aside money for small repairs and upgrades, new window treatments and furniture that suits a warm climate. If you bought a house, budget for pool service, lawn care and pest control. If you bought a condo, check when the next HOA budget is approved and whether fees are expected to rise.
Finally, remember the homestead exemption. Filing by March 1 of the year after you buy can save you a meaningful amount on property taxes every year you live in the home.
You don’t have to do it alone
A good agent, lender and inspector will guide you through every step. Doorstep’s buyer agents host a free monthly first-time buyer workshop — contact us to save your seat.
Ready to start? Run the numbers on any Doorstep listing, read our rent vs. buy guide or meet the agents who will walk you through every step.